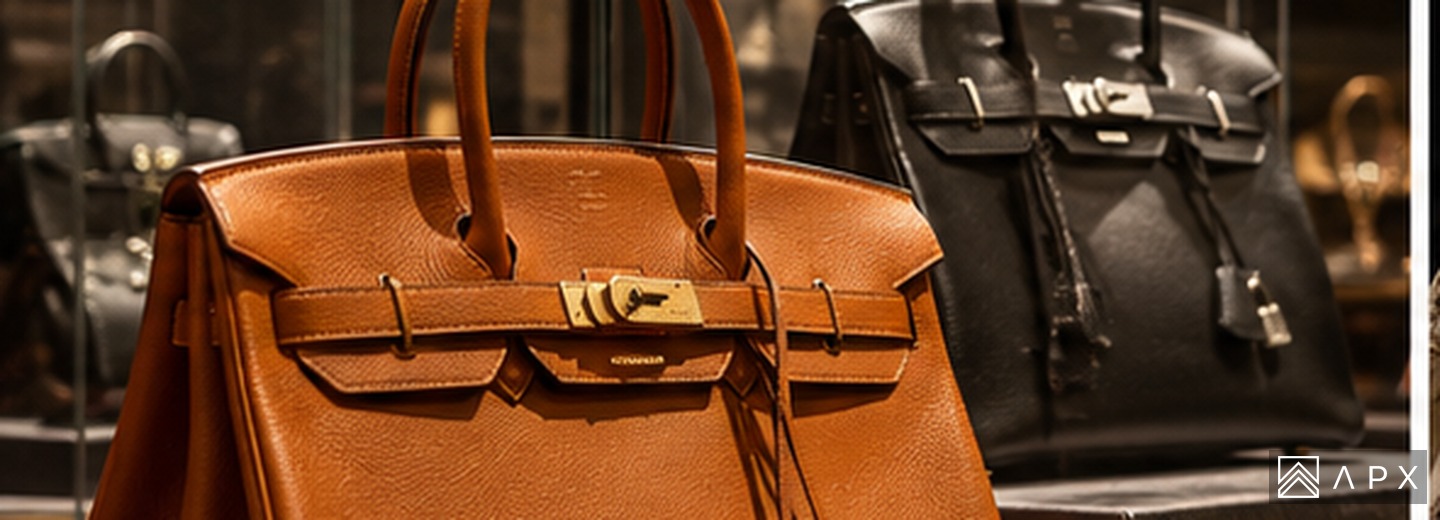
Record Hermès results have pushed handbags deeper into the collectibles market. APX separates unique provenance from repeatable investment characteristics.
Executive Summary
The handbag market has produced spectacular headlines. Jane Birkin’s original Birkin sold for a record $10.1 million in 2025, while Christie’s 2026 Paris handbag sale set multiple category records and achieved €5.84 million.
Those results prove that handbags can be serious collectible objects, but they do not mean an ordinary Birkin will behave like the original prototype. Provenance, rarity, material, size, colour, condition and edition determine whether a bag is a trophy asset or simply an expensive consumer good.
Key Takeaways
- Unique historical provenance can overwhelm normal model-based valuation.
- Christie’s 2026 Paris sale was 98% sold and set multiple records, demonstrating international depth in the top handbag market.
- Limited Hermès models and unusual materials can command large premiums to retail.
- Condition, authenticity, hardware, accessories and service history matter.
- Liquidity is strongest in globally recognised models, but headline records should not be used to value ordinary examples.
The $10.1 Million Birkin Is Not a Comparable
Sotheby’s sale of Jane Birkin’s original bag was a cultural-history event as much as a handbag transaction. It combined direct provenance, design significance, celebrity ownership and one-of-one status. That makes it closer to a museum-grade artefact than a standard production Birkin.
Family offices should therefore resist using record headlines as portfolio marks. The correct comparable is the same model, material, size, colour, year and condition — not the most famous bag ever made.
Where the Repeatable Market Exists
Christie’s 2026 Paris sale provides a better view of the broader high-end market. It achieved a record online handbag total and strong sell-through, with rare Hermès Faubourg, Kelly and special-order models setting category records.
That suggests deep international demand for recognisable, scarce pieces. The repeatable investment case is therefore strongest where rarity can be documented and where a global auction audience understands the model immediately.
Authentication and Condition
Luxury handbags are portable and easy to trade, which also makes them a target for sophisticated counterfeiting. High-value purchases should include specialist authentication, provenance, serial/date-code review where applicable and inspection of hardware, stitching, leather and accessories.
Condition is not binary. Corner wear, scratches, odour, colour transfer, restoration and replaced components can all affect buyer appetite.
Portfolio or Passion Asset?
A collector may rationally buy a bag for use, enjoyment and cultural significance even if financial returns are uncertain. The problem begins when a lifestyle purchase is reported internally as an investment without a realistic resale plan.
For family-office reporting, it can be useful to distinguish “collectible lifestyle assets” from financial assets and apply conservative valuations net of auction fees and selling costs.
APX Perspective
Handbags now have a credible global auction market, but the investable edge lies in rarity and provenance, not the logo alone. The best pieces behave more like design collectibles; the ordinary pieces remain luxury goods.
Frequently Asked Questions
What is the most expensive handbag sold at auction?
Sotheby’s reported that Jane Birkin’s original Hermès Birkin sold for $10.1 million in 2025.
Do Birkins always rise in value?
No. Performance varies by model, rarity, material, condition, purchase price and market demand.
What should a collector keep?
Original packaging, receipts, accessories, service records and any provenance documentation can support future authentication and resale.
Related APX Intelligence
Sources & Further Reading
APX Intelligence is editorial information only and does not constitute investment, legal, tax or financial advice. High-value physical assets can be illiquid, costly to insure and store, and may involve jurisdiction-specific legal or tax considerations.